
Table of Contents
- What Your Tax Preparation Checklist Must Cover in 2026
- Small Business Tax Deductions 2026: What You Can Write Off
- IRS Tax Filing Deadlines 2026 Every Small Business Must Know
- Tax Document Organization Tips for Business Owners
- Best Tax Preparation Software for Small Business in 2026
- Modern Tax Issues: Remote Teams, Digital Assets, and AI Tools
- Post-Filing Audit Readiness and Tax Planning Year-Round
- Conclusion
Last Updated: August 16, 2026
What Your Tax Preparation Checklist Must Cover in 2026
A solid small business tax preparation checklist 2026 is the difference between a smooth filing season and a costly scramble through receipts. Businesses that treat tax preparation as an ongoing discipline pay less than those who treat it as a once-a-year event. This guide covers every major category you need to address before filing, including digital assets, remote teams, and AI-driven accounting tools.
Required Tax Forms and Documentation
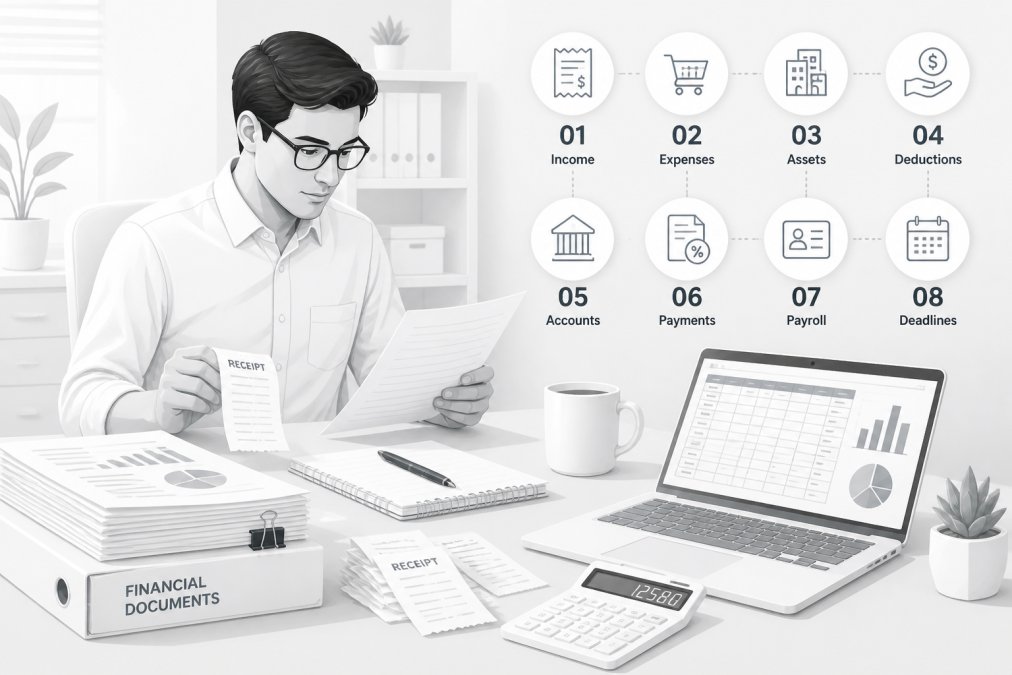
Confirm you have every required form before you touch a return. Missing a single document mid-preparation causes filing delays and amended returns.
Core documents most small businesses need:
- EIN confirmation – Your tax identification number appears on every federal filing.
- Prior year tax returns – Keep the last three years accessible for baseline and carryforward items.
- W-2 forms – Required for any employee paid wages during the fiscal year.
- 1099-NEC forms – Issue for any contractor paid $600 or more.
- Schedule C – Sole proprietors report profit or loss and deductible expenses here.
- Business entity type documentation – S-corps, LLCs, and partnerships file differently.
- Sales tax records – Reconcile against remittances before filing.
According to the IRS Small Business and Self-Employed Tax Center, maintaining organized records throughout the year is the single most effective way to reduce your tax liability and prepare an accurate return.
Income and Revenue Records
Every dollar your business received during the tax year needs to be accounted for, regardless of source.
Pull together:
- Bank statements for all business accounts (12 months)
- Payment processor reports (credit card, ACH, digital wallets)
- Invoices issued and collected
- 1099-K forms from third-party settlement organizations
- Records of returns, refunds, and allowances
A common mistake is treating revenue as whatever landed in your bank account. Accrual-basis businesses recognize revenue when earned, not when paid. If your bookkeeping method doesn’t match how you file, your return will have errors.
Small Business Tax Deductions 2026: What You Can Write Off
Most small business owners overpay taxes because they don’t document what they’re legally entitled to deduct.
Commonly missed deductible expenses:
- Home office deduction (calculated by square footage or simplified method)
- Business-use portion of vehicle expenses (actual cost or standard mileage rate)
- Professional development, subscriptions, and software
- Health insurance premiums for self-employed individuals
- Startup costs for businesses in their first or second year
- Bank fees, merchant processing fees, and business loan interest
- Marketing and advertising spend
The home office deduction is one of the most underused deductions available to sole proprietors and LLC owners. To qualify, the space must be used regularly and exclusively for business.
Qualified Business Income Deduction and Other Credits
The Qualified Business Income deduction (QBI) allows eligible pass-through entities to deduct up to 20% of their qualified business income. This is one of the most significant tax credits available to small businesses, with income thresholds and business-type restrictions worth reviewing carefully each year.
Beyond QBI, review whether your business qualifies for:
- The Work Opportunity Tax Credit (WOTC) if you hired from targeted groups
- Energy efficiency credits if you made qualifying improvements to business property
- Research and development credits if your business conducts qualifying R&D activities
The IRS guidance on the QBI deduction outlines the specific income limits and phase-out rules for 2026. These thresholds adjust annually, so checking current figures before filing is essential.
Asset Depreciation and Capital Expenditures
Capital assets are not fully deductible in the year of purchase. Instead, they depreciate over time according to IRS schedules.
Two accelerated options:
- Section 179 expensing – Deduct the full cost of qualifying equipment in the year it’s placed in service, up to the annual limit.
- Bonus depreciation – Allows an additional first-year deduction on qualifying assets. Verify the current rate for tax year 2026.
Maintain a fixed asset register tracking purchase date, cost, depreciation method, and accumulated depreciation for every capital asset.
IRS Tax Filing Deadlines 2026 Every Small Business Must Know
Missing a tax filing deadline is one of the most avoidable and expensive mistakes a business owner can make. Penalties accrue quickly, and the IRS does not waive them for ignorance.
| Business Entity | Return Due Date | Extension Deadline |
|---|---|---|
| Sole Proprietor (Schedule C) | April 15, 2026 | October 15, 2026 |
| Partnership (Form 1065) | March 17, 2026 | September 15, 2026 |
| S-Corporation (Form 1120-S) | March 17, 2026 | September 15, 2026 |
| C-Corporation (Form 1120) | April 15, 2026 | October 15, 2026 |
| Single-Member LLC (Schedule C) | April 15, 2026 | October 15, 2026 |
A tax return extension gives you more time to file, not more time to pay. If you owe taxes, payment is still due by the original deadline.
Requesting an extension is smart when records aren’t ready. Failing to request one and filing late is not. The failure-to-file penalty is typically steeper than the failure-to-pay penalty.
Estimated Quarterly Tax Payments Schedule
Self-employment tax is often misunderstood. Because no employer withholds taxes on your behalf, the IRS requires quarterly estimated payments throughout the year.
The 2026 estimated quarterly tax payment due dates:
- Q1: April 15, 2026
- Q2: June 16, 2026
- Q3: September 15, 2026
- Q4: January 15, 2027
Underpaying estimated taxes triggers a penalty. The safe harbor rule generally protects you if you pay at least 100% of last year’s tax liability (or 110% if your prior-year adjusted gross income exceeded a certain threshold). Review the IRS Form 1040-ES instructions for estimated taxes to calculate your obligations accurately.
Tax Document Organization Tips for Business Owners
Disorganized records are not just an inconvenience during filing season. They’re a liability if the IRS requests documentation.
A practical document organization system:
- Separate business and personal finances completely. A dedicated business checking account and credit card eliminates the most common bookkeeping headache.
- Digitize receipts immediately. Use a scanning app to capture receipts at point of purchase.
- Categorize expenses in real time. Assign every transaction to a deductible expense category as it happens.
- Reconcile monthly. Match bank statements to bookkeeping records every month.
- Retain records for at least seven years. The IRS generally has three years to audit, but that window extends to six years if substantial underreporting is suspected.
Payroll Records and Employee Tax Information
If you have employees, payroll records are among the most scrutinized documents in any IRS examination. Every W-2 issued must match your payroll tax deposits exactly.
Keep on file for each employee:
- Form W-4 (withholding elections)
- Pay stubs and payroll registers
- Form 941 (quarterly payroll tax returns)
- Form 940 (annual FUTA return)
- Records of all payroll tax deposits
The IRS requires payroll records to be kept for at least four years after the tax due date.
Bookkeeping, Reconciliation, and Audit Trail Best Practices
A clean audit trail is your best defense against IRS scrutiny. An audit trail is the documented record showing how every financial transaction was recorded, categorized, and reported.
What a strong audit trail includes:
- Source documents (invoices, receipts, contracts)
- Bank and credit card statements
- Journal entries with dates, amounts, and categories
- Reconciliation reports showing your books match your statements
- Any adjustments made and the reason for them
The goal of bookkeeping isn’t just accuracy. It’s reproducibility. If a third party sat down with your records, they should reconstruct every number on your return without asking you a question.
Best Tax Preparation Software for Small Business in 2026
The best tax preparation software depends on your entity type, transaction volume, and whether you’re filing yourself or working with a professional.
General categories:
- DIY filing platforms work well for straightforward sole proprietors with clean books and simple deductions.
- Full-service accounting software integrates bookkeeping, invoicing, payroll, and tax reporting in one system.
- Professional tax software is what enrolled agents and CPAs use, handling multi-state returns and complex entity-level filings.
Software handles tax compliance. Tax strategy is different. A platform calculates what you owe based on what you enter. It will not identify that you’ve been missing the home office deduction for three years or that your entity structure is costing you extra in self-employment tax.
Tax software is a filing tool, not a tax advisor. For straightforward returns, it’s sufficient. For businesses with real complexity, growth ambitions, or IRS issues, professional guidance pays for itself in deductions found and mistakes avoided.
Modern Tax Issues: Remote Teams, Digital Assets, and AI Tools
The small business tax preparation checklist 2026 looks different from checklists written five years ago. Three areas have created new obligations.
Digital Asset and Crypto Tax Reporting
Digital assets, including cryptocurrency, NFTs, and stablecoins, are treated as property by the IRS. Every taxable event generates a capital gain or loss that must be reported.
What this means for your tax preparation:
- Maintain a transaction log for every digital asset purchase, sale, and exchange
- Calculate cost basis using a consistent method (FIFO, LIFO, or specific identification)
- Report all taxable events on Form 8949 and Schedule D
- Mining and staking income is treated as ordinary income at fair market value on the date received
The IRS has increased enforcement focus on digital asset reporting.
Tax Implications of Remote and Distributed Teams
Remote work creates state tax complexity. When employees or contractors work from different states, you may have created a tax nexus, triggering income tax, payroll tax, and sales tax obligations.
Key questions to address:
- Do any of your employees or contractors work from states where your business isn’t registered?
- Have you registered for payroll tax withholding in every state where you have employees?
- Are you collecting and remitting sales tax in states where remote workers may have created economic nexus?
State tax agencies have become more aggressive about identifying businesses with nexus that haven’t registered.
Post-Filing Audit Readiness and Tax Planning Year-Round
Filing your return is not the end of your tax responsibility. Audit readiness is an ongoing posture, not a one-time preparation.
Post-filing practices that reduce audit risk and support tax planning:
- Retain all source documents for at least seven years post-filing
- Respond to IRS notices promptly – most are requests for clarification, not audits
- Review your return for consistency with prior years; large unexplained swings attract attention
- Start tax planning for the next year immediately – decisions made in January have more impact than decisions made in December
- Revisit your entity structure annually – as revenue grows, the optimal entity type changes
The real gap in most small business tax strategies is that tax planning happens reactively. The most effective approach is proactive: meeting with a tax professional mid-year, modeling different scenarios, and making decisions before the year closes.
Using this small business tax preparation checklist as your annual framework keeps you organized, compliant, and positioned to capture every deduction you’re entitled to. The businesses that consistently pay less in taxes aren’t finding loopholes. They’re documenting more carefully, planning earlier, and working with professionals who know what to look for.
Art Marina Tax Firm provides comprehensive tax preparation, bookkeeping, IRS resolution, and year-round business consulting for small business owners at every stage. Whether you’re filing a Schedule C for a side hustle or managing multi-state payroll for a growing team, the team at Art Marina Tax Firm brings the expertise to get your return right and your strategy sharper. Book Now to connect with a tax professional before the next deadline arrives.
Frequently Asked Questions
What documents do I need to give my tax preparer for small business filing?
Bring your gross receipts records, 1099-NEC forms received, W-2 forms if you have employees, prior year tax returns, payroll records, bank statements, records of deductible expenses, and your EIN. If you own capital assets, include depreciation schedules. The more organized your bookkeeping records are before your appointment, the faster your preparer can identify every deduction and reduce your tax liability accurately.
What are the most common small business tax deductions for 2026?
Common small business tax deductions for 2026 include home office expenses, vehicle mileage, business insurance premiums, software subscriptions, professional services, startup costs, and retirement plan contributions. Self-employed owners can also deduct the employer-equivalent portion of self-employment tax. The qualified business income (QBI) deduction remains available for eligible pass-through entities, potentially reducing taxable income by up to 20 percent. A tax preparer can confirm which deductions apply to your business entity type.
What are the key IRS tax filing deadlines for small businesses in 2026?
For the 2025 tax year filed in 2026: sole proprietors and single-member LLCs filing Schedule C face a March 15 or April 15 deadline depending on entity type. S-corporations and partnerships must file by March 17, 2026. Quarterly estimated tax payments are due April 15, June 16, September 15, 2026, and January 15, 2027. Missing these dates triggers penalties, so mark them on your calendar now or request a tax return extension before the deadline passes.
How do I organize my financial records for tax season?
Start with a dedicated folder system, either physical or digital, separating income records, deductible expense receipts, payroll records, and asset purchase documents. Reconcile your bank and credit card statements monthly rather than waiting until filing time. Use a consistent chart of accounts in your bookkeeping software throughout the fiscal year. Maintaining a clear audit trail of every transaction makes tax compliance straightforward and protects you if the IRS ever requests documentation.
Do I need to report cryptocurrency on my small business tax return?
Yes. The IRS treats digital assets as property, so any crypto received as business income must be reported at fair market value on the date received. Sales or exchanges of crypto trigger capital gains or losses. Businesses accepting crypto payments should record each transaction's value in dollars at the time of receipt. Failing to report digital asset activity is one of the IRS's current enforcement priorities, so accurate recordkeeping is essential for tax compliance.
Is it worth hiring a tax firm instead of using tax software myself?
Tax software handles straightforward returns well, but it only finds deductions you already know to enter. A tax preparer actively reviews your business structure, expenses, and prior year returns to find overlooked savings and flag risks. For small business owners with employees, inventory, capital assets, or IRS issues, professional guidance typically recovers more in deductions than it costs. Year-round support also means your tax planning happens continuously, not just at filing time.
This article was written using GrandRanker