
Table of Contents
- What Changed for Tax Deductions in 2026
- Itemized vs Standard Deduction Calculator: Which Path Saves More
- Common Tax Deductions for Employees Most People Miss
- How to Find Tax Deductions as a Self-Employed or Gig Worker
- Tax Deduction Checklist for Major Life Events
- Best Tax Deduction Tracking Apps to Stay Organized Year-Round
- Charitable Contributions and Retirement Account Deductions
- Conclusion
Last Updated: August 15, 2026
Most people leave money on the table at tax time, not because deductions don’t exist, but because they never knew to look. At Art Marina Tax Firm, we work with individuals and small business owners year-round to uncover the write-offs that standard software misses. This guide walks you through how to find tax deductions 2026 has to offer, from updated standard deduction amounts to the deductions gig workers almost always overlook.
Tax deductions 2026 filers can claim have shifted due to inflation adjustments, making this a year where reviewing your approach carefully pays off. Here’s what most guides get wrong: they list the deductions but skip the strategy. This guide does both.
What Changed for Tax Deductions in 2026
The biggest driver of change in the tax code from year to year is inflation adjustment. The IRS uses a formula tied to the Chained Consumer Price Index to adjust standard deduction amounts, tax bracket thresholds, and contribution limits annually. When brackets shift upward, some taxpayers find themselves in a lower effective rate without changing their income at all, a legitimate tax relief opportunity requiring zero additional planning.
Standard Deduction Amounts for 2026
The standard deduction is the fixed dollar amount the IRS allows you to subtract from your adjusted gross income before calculating your tax liability. For 2026, refer to the IRS official standard deduction guidance for the most current figures, as amounts vary by filing status.
Filing status determines your deduction amount:
- Single filers and married filing separately: Lowest standard deduction tier
- Head of household: Higher than single, designed for qualifying single parents
- Joint filers (married filing jointly) and qualifying surviving spouses: Highest standard deduction tier
Taxpayers aged 65 or older, or those who are legally blind, qualify for an additional standard deduction amount. Always verify current amounts directly with the IRS or a qualified tax professional before filing.
Federal Income Tax Brackets and Marginal Rates
Federal income tax uses a progressive bracket system where your marginal tax rate applies only to income within each bracket, not your entire taxable income. For 2026, the IRS publishes updated bracket thresholds reflecting the annual inflation adjustment. A taxpayer earning the same gross income in 2025 and 2026 may owe slightly less in 2026 if bracket thresholds shifted upward. Check the IRS Revenue Procedure for annual inflation adjustments for confirmed 2026 bracket figures.
Itemized vs Standard Deduction Calculator: Which Path Saves More
Choosing between itemized deductions and the standard deduction is the single most consequential decision most taxpayers make. The rule is simple: take whichever is larger.
Itemized deductions are the sum of specific qualifying expenses you report on Schedule A. The standard deduction is a flat amount. If your qualifying itemized expenses exceed the standard deduction for your filing status, itemizing saves more.
| Scenario | Likely Better Option | Key Trigger |
|---|---|---|
| Homeowner with mortgage interest + high property taxes | Itemize | SALT + mortgage exceeds standard deduction |
| Renter with no major deductible expenses | Standard deduction | Itemized total falls short |
| High charitable contributions + medical expenses | Itemize | Total exceeds standard deduction threshold |
| Single filer, no mortgage, modest donations | Standard deduction | Simplest path, lower itemized total |
| Self-employed with business deductions | Both paths possible | Business deductions go on Schedule C, separate from itemizing |
When Itemizing Beats the Standard Deduction
Itemizing makes sense when your deductible expenses add up to more than the standard deduction for your filing status. Common itemized deductions include mortgage interest, state and local taxes, charitable contributions, and qualifying medical expenses exceeding the AGI threshold. A common mistake is failing to aggregate smaller deductible expenses throughout the year, medical bills, professional dues, and charitable donations each feel small in isolation but together can push you past the standard deduction threshold.
Keep a dedicated folder (physical or digital) for receipts tied to potential itemized deductions. Medical expenses, charitable donation receipts, and property tax statements are the most commonly forgotten at filing time.
SALT Deduction Limits and What They Mean for You
The State and Local Tax (SALT) deduction allows taxpayers who itemize to deduct state income taxes or state sales taxes, plus local property taxes. The current federal cap applies to joint filers and single filers alike. For the most current cap amount, consult the IRS instructions for Schedule A. Taxpayers in high-tax states feel this cap most acutely. If your combined state income tax and property tax already hits the cap, additional state taxes generate no additional federal deduction.
Common Tax Deductions for Employees Most People Miss
Most employees assume their employer handles everything. Several deductions remain available to W-2 employees that don’t require itemizing or running a business.
Student Loan Interest and Education Expenses
Student loan interest is one of the most underused deductions for younger taxpayers. Qualifying taxpayers can deduct interest paid on federal and private student loans, subject to income phase-out limits. This deduction reduces your adjusted gross income directly, meaning you don’t need to itemize to claim it. Check the IRS Publication 970 on education tax benefits for current income thresholds.
Health Savings Account Contributions
A Health Savings Account (HSA) is a tax-advantaged account available to taxpayers enrolled in a qualifying high-deductible health plan. HSA contributions are deductible above the line, reducing your adjusted gross income regardless of whether you itemize. The triple tax benefit makes it one of the most efficient deductions available: contributions are deductible, growth is tax-free, and qualified withdrawals for medical expenses are tax-free.
HSA contributions reduce your taxable income dollar-for-dollar, and unused balances roll over indefinitely. If you’re eligible, this is one of the most efficient write-offs in the tax code.
How to Find Tax Deductions as a Self-Employed or Gig Worker
Self-employed taxpayers and gig economy workers face a different tax landscape than W-2 employees. Gig economy workers are effectively running a small business and file Schedule C, subject to self-employment tax on net earnings. The opportunity for deductions is broader, but the recordkeeping responsibility falls entirely on you.
Home Office Deduction
The home office deduction is available to self-employed taxpayers who use part of their home exclusively and regularly for business. A desk in a bedroom corner where you also watch television does not qualify. A dedicated room used only for work does.
Two calculation methods exist: the simplified method uses a flat rate per square foot of dedicated workspace up to a maximum set by the IRS, while the regular method uses actual expenses (mortgage interest or rent, utilities, insurance) allocated by the percentage of your home used for business. The regular method produces a larger deduction for many taxpayers but requires more documentation. Legitimate home office use is a valid deduction, document it properly and claim it.
Self-Employment Tax, Retirement Plans, and Business Write-Offs
Self-employment tax covers Social Security and Medicare contributions. Self-employed individuals pay both halves, but the IRS allows a deduction for half of the self-employment tax paid, reducing your adjusted gross income.
Retirement plan contributions are among the most valuable deductions for self-employed workers. A SEP-IRA, Solo 401(k), or SIMPLE IRA allows substantial contributions that reduce taxable income significantly. Contribution limits for self-employed retirement plans are higher than standard employee 401(k) limits.
Other common business write-offs include vehicle mileage or actual vehicle expenses for business use, business phone and internet prorated for business use, professional software and subscriptions, marketing and advertising costs, and professional development directly related to your work.
Tax Deduction Checklist for Major Life Events
Life changes create tax deduction opportunities most people don’t realize exist:
- Got married or divorced: Filing status changes; review withholding and deduction eligibility
- Had a child: Child Tax Credit, Child and Dependent Care Credit, and dependent exemption eligibility
- Bought a home: Mortgage interest deduction, property tax deduction, and points paid at closing
- Sold a home: Primary residence capital gains exclusion rules apply
- Started a side hustle or business: Schedule C expenses, self-employment tax deduction, and home office eligibility
- Went back to school: Education credits and student loan interest deduction
- Changed jobs: Job search expenses (in certain situations), unreimbursed moving expenses for qualifying military members
- Retired: Required minimum distributions, traditional IRA contribution rules, and Social Security income taxation thresholds
- Made a large charitable donation: Substantiation requirements for donations over the IRS threshold
Failing to update your W-4 withholding after a major life event can result in a significant underpayment penalty. A life event that changes your filing status or deduction profile should trigger an immediate withholding review.
Best Tax Deduction Tracking Apps to Stay Organized Year-Round
The biggest reason people miss deductions is poor recordkeeping. Tracking apps solve this problem before it starts. Look for apps that offer automatic expense categorization by IRS deduction type, mileage tracking with GPS verification, receipt scanning and storage, integration with accounting software, and year-end tax summary reports.
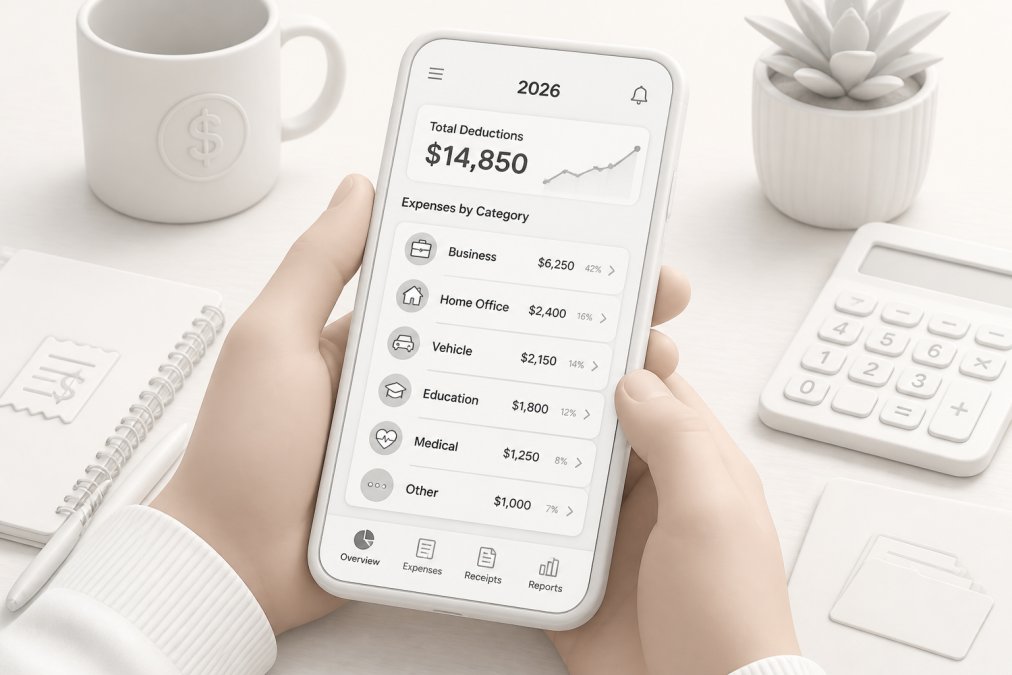
Most tracking apps are most useful when set up at the start of the fiscal year. If you’re starting mid-year, begin now and reconstruct earlier months using bank and credit card statements. Spend 30 minutes configuring expense categories that match your actual deductible expenses before relying on automatic categorization.
Charitable Contributions and Retirement Account Deductions
Charitable contributions to qualifying 501(c)(3) organizations are deductible for taxpayers who itemize. Cash donations require a bank record or written acknowledgment from the organization. Non-cash donations require documentation of fair market value.
Retirement account contributions reduce taxable income regardless of whether you itemize. Contributions to a traditional IRA, 401(k), or SEP-IRA are deductible subject to income limits and plan type.
A practical framework for combining charitable and retirement deductions:
- Max your employer-matched 401(k) first. This is an immediate return on the matched portion.
- Contribute to an HSA if eligible. Triple tax benefit, no "use it or lose it" pressure.
- Fund a traditional IRA or SEP-IRA if income and eligibility allow.
- Batch charitable donations into alternating years if your itemized total fluctuates around the standard deduction threshold.
For taxpayers aged 70½ or older, a Qualified Charitable Distribution (QCD) from an IRA directly to a qualifying charity counts toward the required minimum distribution and is excluded from taxable income, even without itemizing. According to IRS guidance on charitable contribution deductions, substantiation requirements vary based on the type and amount of the donation.
Tax season doesn’t have to mean overpaying. Art Marina Tax Firm provides year-round tax preparation, proactive tax strategy, and IRS resolution support so you never face that complexity alone. Our team works with individuals, gig workers, and small business owners to build customized tax-saving strategies that go beyond what filing software catches. Book Now and put a professional in your corner before the next tax filing deadline.
Frequently Asked Questions
What deductions can I claim on my taxes in 2026?
The deductions you can claim depend on your filing status, income, and life situation. Common options include the standard deduction, mortgage interest, charitable contributions, student loan interest, retirement account contributions, and self-employment expenses like the home office deduction. Employees may also deduct HSA contributions and certain unreimbursed work costs. The best approach is to compare your total itemized deductions against the 2026 standard deduction for your filing status before deciding which path lowers your tax liability more.
What is the difference between a tax deduction and a tax credit?
A tax deduction reduces your taxable income, which lowers the amount of income subject to your marginal tax rate. A tax credit reduces your actual tax liability dollar for dollar. For example, a $1,000 deduction for a taxpayer in the 22% bracket saves $220 in taxes, while a $1,000 tax credit saves the full $1,000. Credits are generally more valuable, but deductions, especially when stacked strategically, can still produce significant tax relief, particularly for small business owners and self-employed filers.
How do I track my expenses for tax deduction purposes?
Consistent tracking throughout the year is far easier than reconstructing records at tax time. Use a dedicated app or folder to log receipts, mileage, and business expenses as they happen. Separate your personal and business accounts so deductible expenses are easy to identify. Many of the best tax deduction tracking apps sync directly with bank accounts and categorize spending automatically. For self-employed filers and gig workers especially, real-time tracking prevents missed write-offs and supports your position if the IRS ever questions a deduction.
What is the most overlooked tax deduction?
For employees, HSA contributions and job-related education expenses are frequently missed. For self-employed taxpayers and gig workers, the home office deduction and the deduction for half of self-employment tax are commonly skipped. Retirement plan contributions, particularly SEP-IRA or Solo 401(k) contributions for the self-employed, are another major overlooked opportunity. Life events like marriage, divorce, having a child, or buying a home also trigger new deductions many taxpayers don't claim because they weren't tracking changes mid-year.
This article was written using GrandRanker