Table of Contents
- Understanding Your Tax Debt and Resolution Options
- IRS Offer in Compromise Requirements and Eligibility
- Setting Up an IRS Installment Agreement Application
- When to Start Hiring a Tax Resolution Professional
- Avoiding Tax Resolution Scams and Protecting Yourself
- Your Rights as a Taxpayer and Resources Available
- Next Steps: Moving Forward With Your IRS Resolution
Last Updated: August 24, 2026
Understanding Your Tax Debt and Resolution Options
Tax debt doesn’t disappear on its own. Whether you owe back taxes, face penalties and interest, or received an unexpected audit bill, understanding what you’re dealing with and what options exist is essential. At Art Marina Tax Firm, we work with individuals and business owners in this situation, and the path forward is clearer than most people realize.
Many people assume they must pay everything immediately or that their situation is hopeless. Neither is true.
What counts as tax debt
Tax debt is any amount you owe to the IRS for unpaid taxes, penalties, or interest. This includes back taxes from prior years, current-year taxes paid late, failure-to-file penalties, failure-to-pay penalties, and daily-accruing interest on unpaid balances.
Your actual tax liability is the base amount. Penalties stack on top, typically 5% per month for failure to pay, up to 25%, plus a separate penalty for failure to file (irs.gov). Interest compounds daily at the federal rate plus 3%. By the time you contact the IRS, the total owed is often significantly higher than the original tax bill. A $5,000 tax liability can become $7,000 or more within two years if penalties and interest accumulate unchecked.
Why resolution matters
Ignoring tax debt makes it worse. The IRS uses wage garnishment, bank levies, property liens, and passport revocation when taxpayers don’t engage. Getting help with IRS resolution early prevents these enforcement actions, stops interest and penalties from compounding, and gives you options. The IRS offers several legitimate paths forward, but you must know they exist and qualify for them.
The moment you realize you owe money to the IRS, contact the agency or a qualified professional. Waiting makes every option harder to access and more expensive overall.
IRS Offer in Compromise Requirements and Eligibility
An offer in compromise is a formal settlement where the IRS accepts less than the full amount you owe. The IRS will only consider an offer if you meet strict criteria.
First, you must demonstrate genuine financial hardship. Your reasonable living expenses must exceed your income, leaving no realistic way to pay the full debt. The IRS calculates this using standardized allowances for housing, food, transportation, and other necessities.
Second, the amount you offer must be reasonable given your financial situation. The IRS uses a formula based on your disposable income and asset equity. If you own a home with $100,000 in equity, the IRS will factor that into the calculation.
Third, you must be compliant going forward. If you’ve filed all required tax returns for the last five years and are current on estimated payments if self-employed, you’re in a stronger position.
The application process requires detailed financial documentation: tax returns, bank statements, mortgage statements, proof of living expenses, and a written narrative explaining your circumstances.
An offer in compromise rejection can actually hurt your position. Once rejected, you’ve signaled to the IRS that you can’t pay, and they may pursue more aggressive collection tactics. Work with a professional before submitting.
Setting Up an IRS Installment Agreement Application
If an offer in compromise isn’t realistic, an installment agreement is often the next option. This is a formal arrangement where you commit to paying your tax debt in monthly installments over time, typically up to 72 months.
The IRS offers several types of installment agreements. A short-term agreement (120 days or less) requires minimal paperwork and is approved quickly. A long-term agreement (more than 120 days) requires financial disclosure and a monthly payment commitment.
Setting up an installment agreement starts with calculating what you can realistically pay each month. Many people underestimate what they can pay, leading to default. Others overcommit and find themselves unable to make payments, which violates the agreement and triggers collection action.
Once you’ve determined a payment amount, submit Form 9465 (Installment Agreement Request) along with financial documentation if your debt exceeds $50,000. The IRS typically approves straightforward requests within weeks.
An installment agreement stops collection action immediately and gives you a predictable payment schedule. The key is committing to a payment amount you can actually sustain for years.
When to Start Hiring a Tax Resolution Professional
Not every tax situation requires professional help. If you owe a small amount, have stable income, and understand the process, handling it yourself is possible. But clear red flags signal you need expert guidance.
Red flags that signal you need help
You should hire a tax resolution professional if you owe more than $10,000, your financial situation is complex (multiple income sources, business ownership, investment income), you’ve already received collection notices or wage garnishment, you’re unsure whether you’ve filed all required returns, your business has payroll tax debt, you’ve had previous disputes with the IRS, or you’re facing an audit alongside tax debt.
Another red flag is emotional overwhelm. If opening IRS letters causes anxiety or you’ve been avoiding the problem for years, professional help is necessary. Tax debt creates psychological weight that compounds the financial problem.
What a tax resolution professional does
A qualified tax resolution professional handles the entire process. They review your tax history, identify missing returns, calculate your total liability accurately, and determine which resolution option best fits your situation.
They also handle communication with the IRS on your behalf. The IRS treats professional representatives differently than taxpayers calling directly. A representative can access account information you can’t and negotiate timelines that might not be available otherwise.
A professional also protects you from costly mistakes. Many people make payment offers that are too generous or commit to installment amounts they can’t sustain. A professional ensures you’re offering what’s actually required, not more.
Avoiding Tax Resolution Scams and Protecting Yourself
The tax resolution industry attracts predators. Scammers specifically target people with tax debt because they’re desperate and often willing to pay for relief.
The most common scam is the "tax relief" company that guarantees they can eliminate your debt or reduce it to pennies on the dollar. No legitimate company can guarantee this. The IRS reviews each case individually. Any company making guarantees is lying.
Another scam involves upfront fees. Legitimate tax professionals charge for their work, but they don’t demand thousands of dollars before doing anything. Many scammers collect payment, do nothing, and disappear.
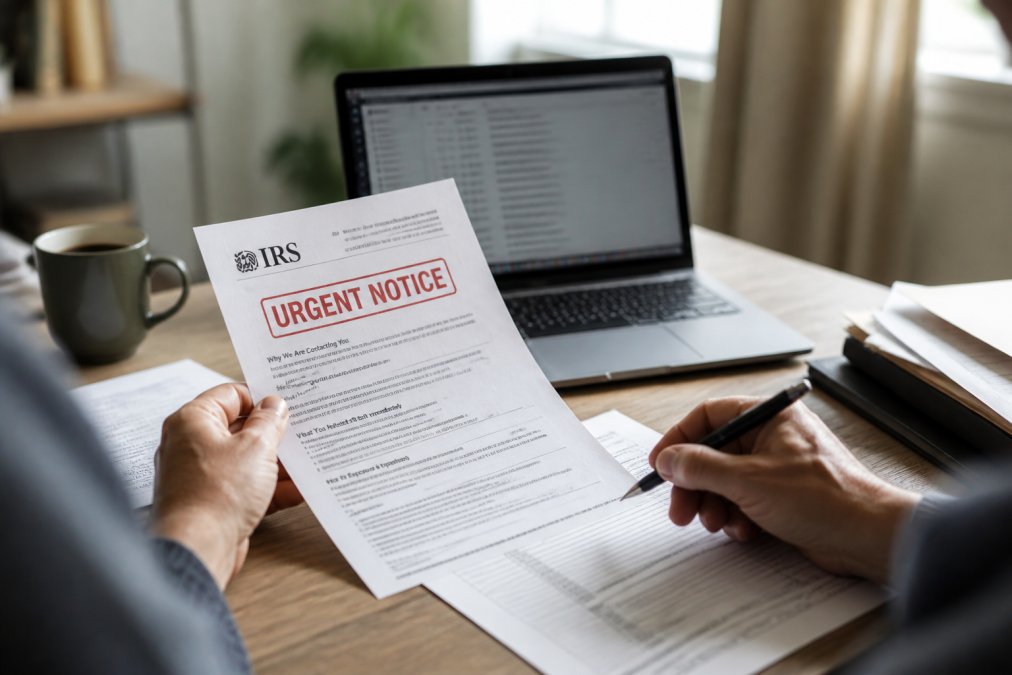
Phishing emails and fake IRS websites are another threat. Scammers create emails that look official and websites that mimic the real IRS site. The real IRS initiates contact by mail, not email.
To protect yourself, verify credentials. Tax professionals should be enrolled agents (EA), certified public accountants (CPA), or attorneys. You can verify an enrolled agent’s status through the IRS website. Ask for references and check them.
If someone contacts you claiming to be from the IRS and demands immediate payment via gift card, wire transfer, or cryptocurrency, it’s a scam. The IRS doesn’t contact taxpayers this way. Hang up and report it to the Treasury Inspector General for Tax Administration (TIGTA).
Your Rights as a Taxpayer and Resources Available
The IRS operates under specific rules, and you have rights throughout the resolution process.
You have the right to representation. You can have a professional represent you before the IRS, and the IRS must communicate with your representative instead of contacting you directly.
You have the right to appeal. If the IRS denies your offer in compromise or proposes an installment agreement you believe is unfair, you can request an appeal. An independent appeals officer will review your case.
You have the right to due process. The IRS must follow specific procedures before taking collection action.
Taxpayer Advocate Service support
The Taxpayer Advocate Service is an independent organization within the IRS that helps taxpayers resolve disputes and navigate the system. If you’re experiencing financial hardship, facing an unfair collection action, or believe the IRS has made an error, you can request assistance.
Contact your local Taxpayer Advocate office or call the national hotline. The service is free and can intervene with the IRS on your behalf. They can request that the IRS delay collection action while your case is reviewed and escalate issues that aren’t being resolved through normal channels.
Low-income taxpayer clinics
Low-income taxpayer clinics are community organizations that provide free tax help to people with limited income. These clinics can help you understand your tax situation, prepare returns, and navigate IRS issues.
To find a clinic near you, visit the IRS website and search for clinics in your area. Eligibility typically requires income below a certain threshold (usually around 250% of the federal poverty level). Services are free, and staff are trained in both tax law and representing clients before the IRS.
According to the IRS Taxpayer Advocate Service annual report, the service resolves thousands of cases annually, with most clients experiencing relief within six months of requesting assistance.
Next Steps: Moving Forward With Your IRS Resolution
Getting help with IRS resolution begins with one decision: to stop avoiding the problem and start addressing it.
Start by gathering your documents. Collect all tax returns you’ve filed, any IRS notices you’ve received, bank statements showing your income and expenses, and documentation of any assets you own.
Next, determine your financial reality. Calculate your actual monthly income and necessary living expenses. Be honest about what you can realistically afford to pay toward tax debt.
Then, decide whether to proceed alone or hire a professional. If your debt is under $5,000, you’re financially stable, and you understand the process, you may handle it yourself. If any complexity exists, professional guidance is worth the investment. Art Marina Tax Firm specializes in these situations and can guide you through each option available to you.
Finally, take action before the IRS takes action. Every month you delay costs you money in penalties and interest. The sooner you engage, the more options remain available.
The IRS Fresh Start Initiative offers simplified processes for people resolving tax debt, including reduced setup fees for installment agreements and expanded offer in compromise eligibility.
Tax debt feels overwhelming because it is complex and the stakes are real. But you’re not alone, and the situation is more manageable than it appears. Getting help with IRS resolution is a process that requires patience, honesty about your financial situation, and often professional guidance. Art Marina Tax Firm provides comprehensive tax preparation, IRS resolution, bookkeeping, and business consulting services tailored for individuals and small businesses. We empower our clients to achieve their financial goals through customized tax-saving strategies and proactive financial planning. The path forward exists. You just need to take the first step. Contact Art Marina Tax Firm today to discuss your specific situation and explore which resolution option makes sense for you.
| Resolution Option | Best For | Timeline | Requirements |
|---|---|---|---|
| Installment Agreement | Stable income, manageable debt | 24-72 months | Monthly payments, financial disclosure if debt >$50K |
| Offer in Compromise | Genuine financial hardship | 6-12 months review | Proof of hardship, all returns filed, reasonable offer amount |
| Currently Not Collectible Status | Temporary hardship | Indefinite (reviewed annually) | Proof of severe financial difficulty, no income |
| Payment in Full | Small debt, available funds | Immediate | Full payment, no ongoing obligations |
=== FAQ ANSWERS (audit these too, same rules) ===
[1] Q: What is the role of the Taxpayer Advocate Service in getting help with IRS resolution?
A: The Taxpayer Advocate Service (TAS) is an independent organization within the IRS that helps taxpayers resolve disputes and provides free assistance when you’re experiencing financial hardship. If you’ve tried to work with the IRS without success, TAS can intervene on your behalf, review your case, and help ensure your taxpayer rights are protected. They can also help if you’re facing collection actions or need representation during an audit.
[2] Q: How do I know if I need a tax professional for IRS resolution?
A: You should consider hiring a tax resolution professional if you owe significant back taxes, face an audit, have received a levy or lien notice, or if the IRS has denied your payment plan request. A professional is especially helpful if you lack time to manage the process yourself, don’t understand your options, or have complex financial situations. A tax resolution officer can handle correspondence, negotiate on your behalf, and ensure compliance with IRS requirements.
[3] Q: What are the main IRS offer in compromise requirements I need to meet?
A: To qualify for an IRS offer in compromise, you must have filed all required tax returns, made estimated tax payments for the current year, and demonstrated that you cannot pay your full tax liability. The IRS evaluates your income, expenses, asset equity, and ability to pay using their Collection Financial Standards. Your offer amount must be at least what the IRS believes it can collect through other means. Most offers are only accepted if they represent the best outcome for both you and the IRS.
[4] Q: Can I negotiate my tax debt with the IRS through an installment agreement?
A: Yes. An IRS installment agreement application allows you to pay your tax debt in monthly payments rather than in full. There are different types: short-term agreements for debts under $25,000, long-term agreements for larger amounts, and streamlined agreements with lower setup fees. The IRS approves most applications if you meet basic requirements and can sustain the monthly payment. A payment plan makes tax resolution manageable and stops collection action as long as you stay current.
Frequently Asked Questions
What is the role of the Taxpayer Advocate Service in getting help with IRS resolution?
The Taxpayer Advocate Service (TAS) is an independent organization within the IRS that helps taxpayers resolve disputes and provides free assistance when you're experiencing financial hardship. If you've tried to work with the IRS without success, TAS can intervene on your behalf, review your case, and help ensure your taxpayer rights are protected. They can also help if you're facing collection actions or need representation during an audit.
How do I know if I need a tax professional for IRS resolution?
You should consider hiring a tax resolution professional if you owe significant back taxes, face an audit, have received a levy or lien notice, or if the IRS has denied your payment plan request. A professional is especially helpful if you lack time to manage the process yourself, don't understand your options, or have complex financial situations. A tax resolution officer can handle correspondence, negotiate on your behalf, and ensure compliance with IRS requirements.
What are the main IRS offer in compromise requirements I need to meet?
To qualify for an IRS offer in compromise, you must have filed all required tax returns, made estimated tax payments for the current year, and demonstrated that you cannot pay your full tax liability. The IRS evaluates your income, expenses, asset equity, and ability to pay using their Collection Financial Standards. Your offer amount must be at least what the IRS believes it can collect through other means. Most offers are only accepted if they represent the best outcome for both you and the IRS.
Can I negotiate my tax debt with the IRS through an installment agreement?
Yes. An IRS installment agreement application allows you to pay your tax debt in monthly payments rather than in full. There are different types: short-term agreements for debts under $25,000, long-term agreements for larger amounts, and streamlined agreements with lower setup fees. The IRS approves most applications if you meet basic requirements and can sustain the monthly payment. A payment plan makes tax resolution manageable and stops collection action as long as you stay current.
This article was written using GrandRanker